
For most negative items—like late payments, charge-offs, or collections—seven years is the magic number. That’s how long they can legally stay on your credit report, counted from the date of the first missed payment (the “original delinquency date”).
I know, seven years sounds like a lifetime in internet years. But think of it this way: it’s less than a decade, and honestly, the impact fades over time. A missed payment from year one hurts way less than one from year six, because your recent good behavior starts to shout louder.
Hey, you know that saying “time heals all wounds”? Credit wounds are no exception—they just take a little longer than a scraped knee. And no, a new payment won’t reset that seven-year clock, so don’t worry about poking the bear.
What About Chapter 7 Bankruptcy or Tax Liens? (Spoiler: They’re Stickier)
Now, if you’ve had a Chapter 7 bankruptcy, that stays for ten years from the filing date. A Chapter 13 bankruptcy? That’s seven years, too, but sometimes lenders treat it more gently since you’re repaying part of the debt. (Ironic, right?)
Unpaid tax liens used to hang around forever, but as of 2018, the credit bureaus changed the rules. Now, paid tax liens disappear after seven years from the payment date. Unpaid ones? They can stay indefinitely—so maybe don’t ignore the IRS. Just a thought.
Oh, and student loan defaults? They follow the same seven-year timeline as other delinquencies, unless you rehab them. Default for nine months, and boom—that stain appears. But once you fix it, the clock starts ticking on the original mess.
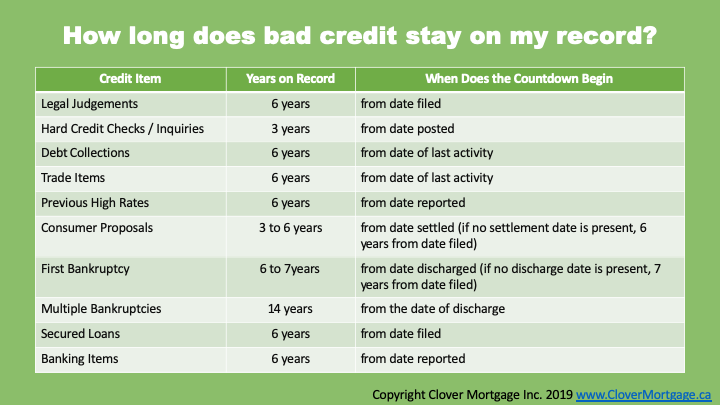 How Long Does Bad Credit Stay On Your Record? - Clover Mortgage Inc.

