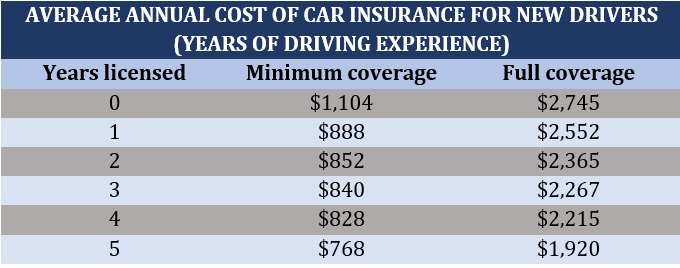
Beyond the car choice, there are moves that make you look like a savvy negotiator to your insurer. First, add a dashcam. Many companies give a small discount if you install one—it’s proof you’re a responsible driver. Second, ask about low-mileage discounts. If you’re only driving to school or work (5,000 miles a year), tell them.
Also, consider paying annually instead of monthly. It’s like buying in bulk at Costco—you save because you’re not paying interest. And don’t be shy about bundling your renters or parents’ home insurance with your car policy. That combo discount can knock 10-15% off.
Finally, take a defensive driving course. It’s boring, yes, like watching paint dry while someone talks about following distance. But it tells insurers, “Hey, I’m not a maniac,” and they reward you with a lower rate for 3-5 years.
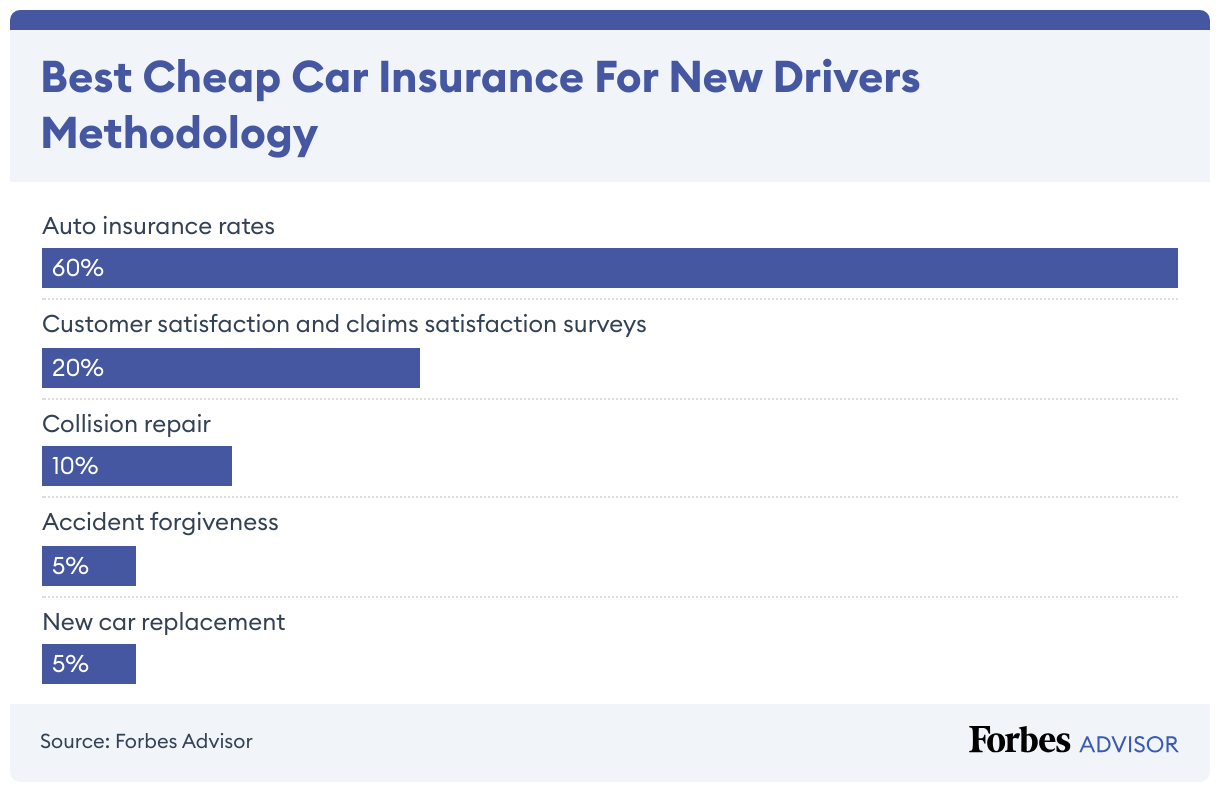 Best Cheap Car Insurance For New Drivers Of 2026 – Forbes Advisor
The Cultural Side of the Road
Think of your first car as a right of passage, not a status symbol. In many countries, new drivers start with a beat-up hatchback, and that’s celebrated. It’s like the first apartment with a futon and a milk crate coffee table—character over flash. Embrace it.
Fun fact: In Japan, there’s a whole genre of “Kei cars”—tiny, low-powered vehicles designed to be cheap to insure and tax. They’re adorable and efficient. We could learn from that. The less horsepower you have, the less you’re tempted to speed.
Remember: every time you see a new driver in a shiny SUV, they’re probably paying more for insurance than their monthly rent. You don’t want to be them. You want to be the person who drives a sensible, safe car and spends the savings on experiences—like a weekend road trip or, you know, rent.

